Project portfolio optimization is the discipline of selecting, sequencing, and funding the set of projects that returns the most strategic value from a fixed pool of money, people, and time. It sits inside strategic portfolio management, the category Gartner®, per our understanding, uses for software that connects investment decisions to business outcomes. Most PMOs already do a version of it once a year, in a spreadsheet, and then hope nothing changes.
Something always changes. A supplier slips, a regulator moves a deadline, a customer cancels, a competitor launches. June 2026 Gartner® research on AI and portfolio risk puts it plainly:
"Today's risks emerge faster than traditional governance cycles can detect, creating blind spots that threaten portfolio value"
That is why the conversation has shifted from annual portfolio selection to continuous portfolio reprioritization. This report covers what project portfolio optimization (PPO) means in practice, the optimization techniques PMOs use, how AI changes the math, and how to build a portfolio that stays aligned with strategic goals when conditions move. It is written for PMO leaders, transformation executives, and heads of capital projects who own the answer to the question "are we working on the right things?".
Our Key takeaways
Project portfolio optimization is a decision discipline, not a spreadsheet exercise. It answers which candidate projects to fund, in what order, given real limits on budget, people, and time.
Strategic portfolio optimization only works when the objective is explicit. A portfolio can maximize value, minimize risk, or balance both, but it cannot do everything at once, and the PMO has to decide.
Capacity is the constraint that breaks most portfolios. Optimization techniques that ignore resource allocation produce plans that look excellent on paper and stall in delivery.
AI makes portfolio reprioritization continuous rather than annual. Gartner 2026 research describes continuous risk sensing and probabilistic forecasting as the capabilities that let PMOs adjust before value erodes.
The best project portfolio optimization tools connect the analysis to live delivery data. A PPO tool that runs on last quarter's numbers optimizes the wrong portfolio.
Project portfolio optimization is a decision discipline
Project portfolio optimization (PPO) is the process of choosing the subset of candidate projects, from everything an organization could do, that delivers the highest strategic value within its constraints. The constraints are usually money, people with specific skills, time, and risk appetite. The output is a ranked, funded, sequenced project portfolio that leadership can defend.
It differs from project portfolio management in scope. Project portfolio management is the ongoing governance of the whole portfolio, from intake through delivery and benefits tracking. Portfolio optimization is the analytical step inside that process where the PMO decides what gets in, what waits, and what stops.
Most PMOs already have the raw ingredients. They hold a backlog of proposals, a budget envelope, a resource plan, and a set of strategic goals from the executive team. What they often lack is a repeatable, data-driven way to trade those things off against each other, and a way to redo the trade-off when the inputs change.
Portfolio prioritisation and portfolio optimization are not the same thing
Portfolio prioritisation ranks projects against each other on a scoring scale, while optimization asks which combination of projects fits inside the constraints and returns the most value. A prioritised list tells you project A scores higher than project B. An optimized portfolio tells you that funding A, C, and F together beats funding A and B, because B consumes the same engineering team that C and F need.
That distinction matters more as portfolios get bigger. With ten projects, a manager can eyeball the trade-offs. With two hundred projects sharing forty scarce skill sets across three business units, the interactions between projects become the whole problem, and only an analytical approach can hold them all in view.
Strategic portfolio optimization starts with clear objectives
Strategic portfolio optimization means building the portfolio around what the enterprise is trying to achieve, not around which departments shouted loudest. The first job is to state the goal in a form the optimizer can score. "Grow revenue in new markets" is a strategy, whereas "weight each project by expected three-year revenue in new markets, capped by our risk tolerance" is a scoring rule.
Cora's guide to the benefits of strategic portfolio management describes the value of evaluating the entire project portfolio against strategic objectives before adding new work. Optimization is how that evaluation becomes systematic. Each candidate project gets scored on its contribution to each strategic goal, its cost, its risk, and its resource demand, and the optimizer finds the mix that aligns every initiative with the strategy.
A single portfolio can hold several competing objectives
Real portfolios rarely have one goal. A manufacturer might want to cut unit cost, launch two new products, and meet a sustainability target in the same year. A defense contractor might need to protect margin on existing programs while investing in capture for the next recompete.
Multi-goal optimization handles this by weighting each goal and finding the portfolio that scores best across the weighted set. The weights are a leadership decision, and making them explicit is often the most valuable part of the exercise. Executives who disagree about priorities discover it during the weighting conversation, not six months into delivery.
Strategic goals should drive project selection, not follow it
A common failure pattern is to approve projects first and then map them back to strategic goals so the slide deck looks aligned. This is portfolio management theatre. Optimization inverts the sequence: the strategy sets the scoring criteria, the criteria score the candidate projects, and the optimizer builds the portfolio.
Cora's article on PMO maturity and how to improve it frames this shift as the move from reporting on projects to shaping which projects exist. PMOs at the higher maturity levels own the intake and selection process, and optimization is the tool they use to run it.
Resource allocation and capacity set the real constraints
Budget is the constraint everyone talks about. Capacity is the constraint that actually breaks portfolios. A portfolio can be perfectly affordable and still fail because it needs 14 certified systems engineers in the same quarter and the organization employs nine.
Effective resource allocation in portfolio optimization treats skills, not headcount, as the unit of capacity. The optimizer needs to know which roles each project consumes, when, and for how long. Then it can detect that the highest-value portfolio is undeliverable and swap in the next-best portfolio that fits the team.
Dependencies change the value of every project
Projects rarely stand alone: a new customer portal depends on the identity platform upgrade, and the plant expansion depends on the zoning permit. Optimization handles this with dependency constraints. Project B can only be selected if project A is selected, or B cannot start until A reaches a milestone.
Ignoring dependencies produces portfolios where the highest-scoring projects are all blocked by low-scoring ones that never got funded. The schedule slips, the benefit case moves out a year, and the optimization was wasted. Cora's article on making data a strategic asset in aerospace and defense describes how integrated program data exposes these dependencies before they become schedule problems.
Adjusting projects mid-flight is part of optimization
Optimization is not only about which projects to start. It includes adjusting projects already underway: descoping one, accelerating another, pausing a third to free capacity for a new priority. A PMO that can only optimize at intake will always be optimizing a stale portfolio.
This is where portfolio reprioritization becomes the operating rhythm rather than the annual event. When a live project's forecast cost rises 30 percent, the question is not just "do we continue?" but "what else in the portfolio changes if we do?" Answering that requires the same analysis, run again, with updated data.
AI turns portfolio reprioritization into a continuous practice
Gartner report "How to Use AI to Improve Portfolio Risk Management and Protect Value" makes the argument directly in our opinion. Traditional portfolio risk management relies on periodic reviews and static risk registers, and that cadence cannot keep up with how fast risks now emerge. The report's central claim is that organizations that redesign portfolio decision making around AI-driven risk intelligence gain a sustained decision advantage over those that deploy AI as a reporting tool.
For portfolio optimization, that redesign has four practical consequences.
Continuous risk sensing replaces the quarterly review
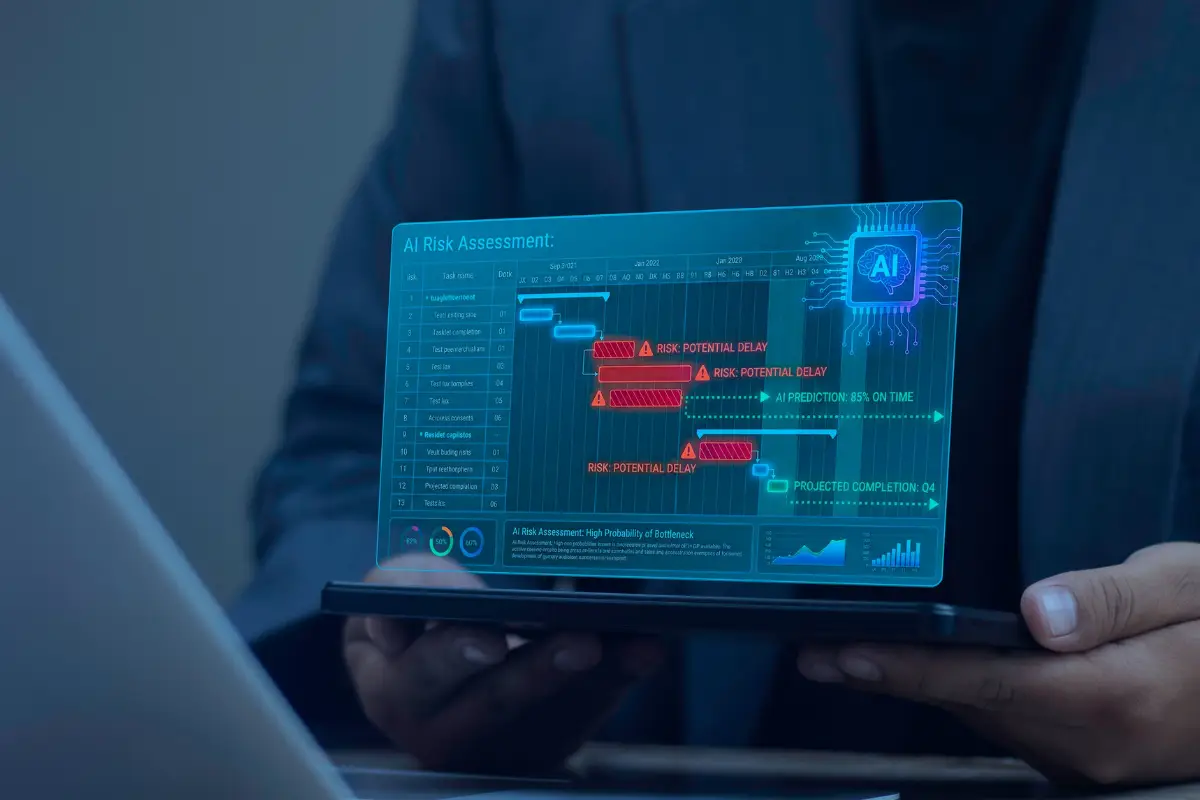
Gartner describes continuous risk sensing as the practice of ingesting both structured data (schedules, budgets, resource utilization) and unstructured data (risk narratives, meeting notes) and using machine learning and anomaly detection to flag emerging risks between formal reviews. When a leading indicator such as schedule variance or dependency delay crosses a threshold, the system triggers an alert.
For the PMO, this means the optimization engine is fed with signals as they happen. A project whose risk profile worsens in week three does not wait until the quarterly steering committee to be reconsidered. The portfolio can be reprioritized while there is still time to redirect the capacity.
Probabilistic forecasting gives the optimizer honest inputs
Every optimization technique is only as good as its inputs, and single-point estimates are a known weakness. Gartner recommendation is to replace them with confidence-based outcome ranges:
"instead of forecasting that an initiative will be completed in September, leaders can assess the likelihood of completion within different timeframes based on current risk conditions"
Feeding ranges rather than points into the optimization changes the answer. A project with a high expected value but a wide outcome range may rank below a steadier project once risk-adjusted value is the objective. Gartner guidance is to evaluate initiatives on risk-adjusted value rather than business cases alone.
AI-driven insights belong inside the portfolio decision, not beside it
The report is careful on this point:
“The value of AI-enabled risk management is realized only when risk intelligence influences -- not replaces -- decisions. AI should augment risk review processes without becoming a checkbox compliance activity”
The PMO still decides; the AI makes the trade-offs visible faster and with better numbers.
Gartner companion research on AI use cases in program and portfolio management, "AI Use-Case Assessment for Program and Portfolio Management Processes" (Peter Clegg, Shivica Mathur and others, 17 July 2026, ID G00851458), notes that
"most PPM organizations are underprepared to integrate advanced AI capabilities due to gaps in AI-ready data, internal process maturity, and change management readiness."
The lesson for optimization is that the data foundation has to come first. An optimizer running on fragmented project, financial, and resource data will produce misleading results with unwarranted confidence.
Portfolio reprioritization aligns to value realization, not delivery status
The final shift Gartner describes is measuring risk and value at the enterprise level. Rather than asking whether each project is on schedule, the PMO
"Map portfolio risks to strategic objectives, benefits, and enterprise KPIs. Measure value at risk at initiative, portfolio, and enterprise levels. Prioritize risk responses based on potential impact to expected business outcomes"
Applied to optimization, this closes the loop. The same strategic goals that drove project selection become the yardstick for whether the optimized portfolio is actually delivering, and the trigger for the next round of portfolio reprioritization when it is not. Cora's article on how AI protects portfolio value from emerging risk goes deeper on building this continuous intelligence layer.
A project portfolio optimization framework for PMOs
The following framework distils the techniques above into a repeatable cycle. It works for a first optimization exercise and for the ongoing reprioritization rhythm that follows.
Step one is a clean inventory of candidate projects and live work
List every proposal and every active project with the same data fields: strategic contribution by goal, estimated cost, expected benefit, resource demand by skill and period, dependencies, and risk rating. Consistency matters more than precision at this stage. A portfolio where half the projects have detailed benefit cases and half have a one-line description cannot be optimized fairly.
Step two sets the goal and the constraints
Agree with leadership on what the portfolio is maximizing and the weights across strategic goals. Then document the hard constraints: total budget, capacity by skill and period, regulatory or contractual must-do projects, and any mutual exclusions. Write these down before running any analysis, because the optimizer will faithfully optimize whatever it is given.
Step three runs the optimizer and builds the portfolio
Use a scoring model for the first pass to remove weak candidates, then apply mathematical programming or a PPO tool to find the best combination under the constraints. Produce two or three alternative portfolios at different budget or risk points so leadership has a real choice. Portfolio construction is a conversation, and the optimizer's job is to make that conversation concrete.
Step four stress-tests the portfolio with scenarios
Run the selected portfolio through the scenarios that worry leadership most: a budget cut, a key supplier failure, a delay in the largest program, a surge in demand from one business unit. Note which projects fall out first and whether strategic coverage survives. If the portfolio collapses under a plausible scenario, revise it now rather than in the quarter when the scenario arrives.
Step five embeds the optimizer in the operating rhythm
Connect the optimizer to live delivery data so that forecast changes, risk alerts, and capacity shifts update the inputs automatically. Set a reprioritization cadence, monthly for most portfolios, plus event-driven triggers for material changes. This is the step that turns a one-off optimization project into strategic portfolio optimization as a standing capability.
Project portfolio optimization examples across industries
The framework looks different depending on what the portfolio contains. Three examples show the range.
Manufacturing PMOs optimize across plants and product lines
A manufacturing PMO typically balances capital projects (new lines, plant expansions), continuous improvement work, and product launches, all drawing on the same engineering and maintenance teams. Optimization here is usually capacity-led: the binding constraint is skilled trades availability by site and quarter. Cora's guide to project portfolio management success in manufacturing describes how consolidating this data from spreadsheets into a single platform is the prerequisite for any meaningful optimization.
Aerospace and defense contractors optimize for margin and recompete position
For government contractors, the portfolio includes funded programs with earned value obligations, internal research and development, and capture efforts for future bids. Optimization must protect margin on committed work while allocating enough investment to win the next contract. Dependencies between programs sharing cleared engineers are the dominant constraint, and Cora's aerospace and defense platform is built around exactly these trade-offs.
Pharmaceutical portfolios optimize against pipeline probability
In life sciences, each candidate project carries a probability of technical and regulatory success that changes as trials report. Optimization weights expected value by that probability and reprioritizes as data arrives. Cora's article on how pharmaceutical PMOs protect pipeline ROI shows how modeling go/no-go decisions against financial thresholds keeps the portfolio's aggregate risk-return profile on target.
How Cora Systems can help
Cora provides project portfolio management software that turns portfolio optimization from an annual spreadsheet exercise into a continuous, data-driven practice. The platform centralizes project, financial, resource, and risk data in one system so that portfolio optimization always runs on current numbers rather than last quarter's export.
Cora's strategic portfolio management capabilities let PMO leaders score candidate projects against strategic objectives, compare alternative portfolio configurations with what-if scenario tools, and see the downstream effect on schedule, cost, and strategic coverage before committing. Resource and capacity planning maps skill availability against pipeline demand so that the selected portfolio is deliverable, not just affordable.
The Cora Data Analytics and AI layer applies machine learning to predict risk, slippage, cost overruns, and resource conflicts across the portfolio, which is the continuous risk sensing 2026 Gartner research describes as per us. Combined with Cora Data Hub, which harmonizes PPM, ERP, CRM, and HR data into AI-ready datasets, it gives PMOs the foundation Gartner identifies as the first prerequisite for AI-enabled portfolio decisions.
The portfolio you optimize today needs to hold tomorrow
Project portfolio optimization used to be a planning-season activity: gather the proposals, score them, fund the top of the list, and revisit next year. That approach assumed the inputs would stay roughly true for twelve months. They no longer do, and 2026 Gartner research is explicit that periodic reviews now leave value on the table.
The PMOs pulling ahead treat optimization as a live capability. They keep candidate projects, capacity, dependencies, and risk in one connected dataset, run the optimization whenever conditions shift, and bring executives risk-adjusted options rather than a single plan. Strategic portfolio optimization becomes how the organization decides, not a report it produces.
Cora gives PMO leaders the platform to do this: centralized portfolio data, scenario comparison, capacity planning, and AI-driven risk sensing in one system. Request a demo to see how Cora supports project portfolio optimization and continuous portfolio reprioritization for your organization.
References
Gartner, How to Use AI to Improve Portfolio Risk Management and Protect Value, Cynthia Phillips, Zahid Kisa, 30 June 2026.
Gartner is a trademark of Gartner, Inc. and/or its affiliates.